Section 179 Commercial Roof Tax Deduction: How Maine Business Owners Write Off 100% of Roof Costs
Historically, replacing a commercial flat roof required a painful 39-year straight-line depreciation schedule. Thanks to the expanded IRS Section 179 framework, commercial property owners across Maine can now write off up to 100% of their roofing project within the very first tax year.
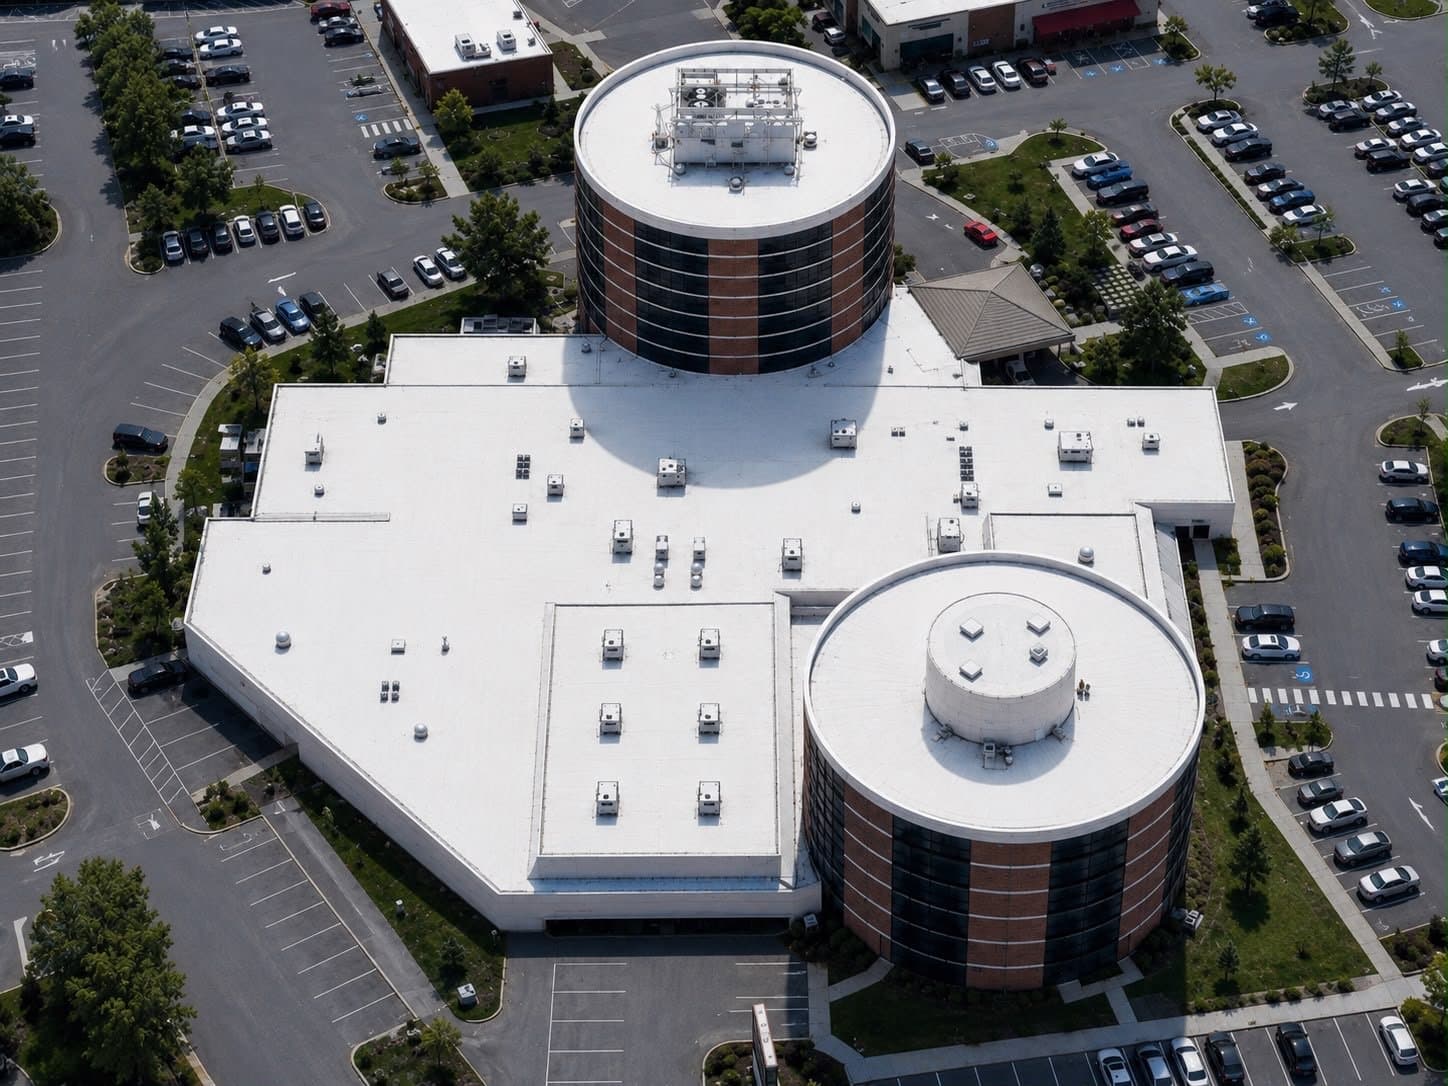
120,000 sq ft Commercial Membrane in South Portland, ME — Full Year-One Deduction Captured
The Bottom-Line Financial Advantage
If your commercial facility in Portland, Lewiston, Bangor, or Saco invests $150,000 in a new TPO, EPDM, or standing seam metal roof, traditional IRS rules only allowed you to deduct approximately $3,846 per year over 39 years. Under current Section 179 rules, you can deduct the entire $150,000 in Year One, resulting in up to $31,500 – $52,500 in immediate cash savings (depending on your federal and state tax bracket).
What Qualifies Under Section 179 for Commercial Roofing?
Under IRS Code Section 179, qualifying property includes "Qualified Improvement Property" (QIP) and specific improvements to non-residential real property placed in service after the date the building was first placed in service. This specifically covers:
- Commercial Flat Roofs
Complete tear-offs and replacements using TPO (Thermoplastic Polyolefin), EPDM rubber, or PVC membranes.
- Standing Seam Metal
Heavy-gauge structural and architectural metal roofing installed on commercial warehouses and retail plazas.
- Silicone Roof Coatings
Fluid-applied high-solids silicone coatings that restore flat roofs can often be treated as 100% operational repairs.
- Thermal Insulation Upgrades
Adding polyiso (polyisocyanurate) rigid foam insulation boards to meet Maine’s R-30 commercial energy codes.
Comparison: Old 39-Year Depreciation vs. Section 179 Expensing
| Cost of Commercial Roof | Traditional 39-Yr Method | Section 179 First-Year Deduction | Estimated Cash Tax Savings* |
|---|---|---|---|
| $75,000 (Small Commercial / Strip Mall) | $1,923 / year | $75,000 (100% year one) | $15,750 – $26,250 |
| $150,000 (Warehouse / Hotel) | $3,846 / year | $150,000 (100% year one) | $31,500 – $52,500 |
| $350,000 (Large Distribution Center) | $8,974 / year | $350,000 (100% year one) | $73,500 – $122,500 |
*Assumes an effective federal + Maine state combined corporate/pass-through tax bracket of 21% to 35%. Always consult with your certified CPA or tax advisor for your entity’s exact calculation.
Critical Timing: The "Placed in Service" Deadline
To claim the tax deduction on your upcoming return, the roof replacement or coating must be fully completed and "placed in service" before midnight on December 31st of the tax year.
Documentation Provided for Your CPA & Accounting Records
Tax deductions require rigorous audit-proof documentation. When you partner with Maine Roofing Scapes & Repairs, we provide:
- Itemized Commercial Invoicing: Clear separation of tear-off labor, membrane materials, R-value insulation, and flashing assemblies.
- Certificate of Completion & Date of Service: Official engineering sign-off stating the exact date the system was placed into operational service.
- Manufacturer NDL Warranty Paperwork: 20 to 30-year No Dollar Limit warranty documents corroborating long-term capital asset qualification.
Planning a Commercial Roof Project in Maine?
Get an itemized commercial proposal, core sampling analysis, and Section 179 qualification packet from Hassan and our commercial roofing team.